|
|||
|
Let’s Talk About Your Mortgage Goals
Buying, renewing or refinancing? Let’s explore mortgage options that fit your goals and financial situation.
Jag Dhamrait
Mortgage Agent Level 2
Phone: 647-883-7790
Email: jag@jagdhamrait.com
Financial Tips 22 Oct
|
|||
|
Buying, renewing or refinancing? Let’s explore mortgage options that fit your goals and financial situation.
Jag Dhamrait
Mortgage Agent Level 2
Phone: 647-883-7790
Email: jag@jagdhamrait.com
Mortgage Tips 18 Jun
Extra mortgage payments can help reduce interest and shorten your amortization, subject to your mortgage terms.
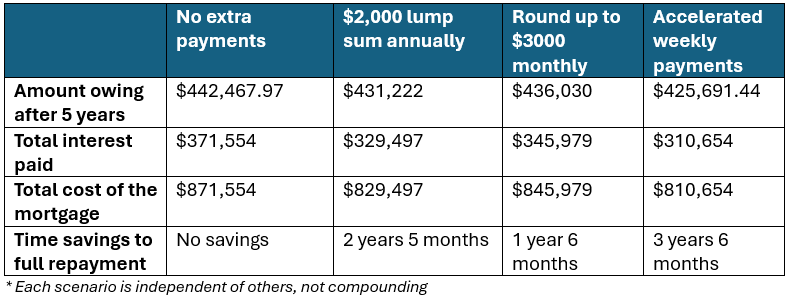
Small extra mortgage payments can make a big difference over time by helping reduce interest and shorten your amortization.Having some extra cash on hand might give you some breathing room on rising gas and food prices, building an emergency fund, or even the ability to make a big purchase you’ve delayed. But – should you pay down your mortgage instead? If you’re considering paying down your mortgage, you’re in luck, because today we’re going to look at how a lump sum payment can transform your mortgage future. Base Case Scenario Here we’re going to look at a mortgage with a $500,000 balance at a rate of 4.99% and a 25-year amortization. In this scenario, your monthly payment would be $2,905.18. If we fast forward 25 years to the end of that mortgage, having made no lump sum payments, you’ll have paid $371,554 in interest and a total of $871,554 in payments for your $500,000 mortgage. Although your rate will vary over the course of your mortgage, in this example we’re going to keep it consistent at 4.99%. Payment Options When we’re talking about paying down your mortgage early, there are three main ways you can do this. The first is to save a lump sum of cash, which you put down all at once, one time per a year (for example, on your mortgage anniversary). You don’t have to make this payment every year, but you likely have the option to put down a flexible amount of cash with upper and lower limits every year of your mortgage. The second option is to round up your regular payments to a set amount. Again, there will be upper and lower limits on how much you can pre-pay, but you’ll likely be able to round up by a couple hundred dollars or to the nearest $100, for example. The third option is to go with accelerated payments, which are normally offered weekly or bi-weekly. Here the lender will calculate the specific amount for you. Each of these options will help you pay less in interest over the lifetime of your mortgage, with varying impact on the total amount of interest. Below is a chart showing how these three prepayment types can change your mortgage.
|
 |
|
As you can see, even a small monthly increase in your payment can save you tens of thousands of dollars on your mortgage. The biggest impact you can make on your own financial future is to change your payment frequency – the more often you pay, the less interest you pay, and the sooner you pay off your mortgage in full! Even if you don’t have a new mortgage, you can start any of these strategies at any time. Whenever you do start prepaying, you’ll start saving time and money over the rest of the term of your mortgage. Be Aware: It’s important to consult your lender about what prepayment types and amounts allowed within your current mortgage. Many lenders set prepayment amounts as a percentage of your outstanding mortgage balance, although some lenders offer more unique options like doubling a payment. If you want to run this scenario for your own mortgage, with whatever numbers you have, and different prepayment amounts, I’ve got great news. You can download my app and do it all – easily and for free – whenever you want. And if you have questions, you can DM or call me right in the app for help! |
Buying, renewing or refinancing? Let’s explore mortgage options that fit your goals and financial situation.
Jag Dhamrait
Mortgage Agent Level 2
Phone: 647-883-7790
Email: jag@jagdhamrait.com
Economic News 3 Jun
|
||||
|
||||
|
Home Tips 24 Mar
A contemporary kitchen renovation remodeling featuring a center island, hardwood floor and quartz counter.
Minimalism is dead.
In 2026 we’ve moved on, adding colour, vibrancy, new features and personality galore into our homes.
Here are the biggest trends you can keep your eyes (and budget) set on this year:
Grandma Chic: If your birth year starts with 19, you’ll probably feel nostalgic about this trend. Things like florals, ruffles and pleated skirts are back on couches and chairs. Lamp shades, antique clocks, China cabinets and anything else you saw in your grandma’s house in the 80’s is back in style. Your entire house doesn’t need grandma’s approval, but it’s time to proudly and stylishly display any heirlooms she passed down.
Dark Design: Terracotta, dark green, chocolate brown, darker woods… the stylish home has plenty of these colours in 2026. If you want to try it, consider painting your existing cabinetry, adding a chair or couch in a moody shade, or even choosing an area rug that does double duty in style and function while it hides the fact you haven’t vacuumed this week (or month).
Feeling Blue: Blue may not be the Pantone colour of 2026 – but it’s everything in fashion, design, social media content, makeup, even dining. Any shade will do, from icy to electric. It’s super easy to add to your home with things like furniture, dishes, artwork, rugs, or even knickknacks (those are back too… keep reading).
Bidets: Thanks to the explosion in bidet popularity, it’s easy to find an attachment, toilet seat, sprayer or entirely new toilet to bring the bidet lifestyle into your home. Plus, they reduce toilet paper use, saving your home plumbing and the environment! They’re fairly easy to install yourself so if you’re keen on trying one, a trip to your local hardware store is probably all you need.
Walls Are the Art: Wallpaper is back, baby! There are infinite cool patterns and colours to choose from, including some really interesting and personal choices. And don’t forget the fifth wall to every room – the ceiling! Paint it or wallpaper it too, adding drama, interest, and even heights to the space.
Personal Storytelling: This unique approach is about telling your own story, piece by piece. Any room can feel welcoming because nothing is too precious or perfectly styled. It won’t happen overnight though. It’s a rebellion against fast fashion and staged decorating, as you collect everything over your lifetime rather than in one trip to Pottery Barn. Display your travel souvenirs, favourite knickknacks, unique furniture and thrifted gems and enjoy sharing a memory or telling an origin story of your favourite treasures to your guests.
What’s Out
If you’re looking to thoughtfully declutter as you modernize or redecorate your home, here are the top three things to part with.
Fake plants. And its cousin, the 2000’s oversized vase with dried wheat.
Mass produced wall art. That print of le chat noir or Campbell soup are heading for retirement (or the attic for when they come back in style).
Word art. We don’t live laugh or love this look anymore.
I’d love to hear what interior decorating styles and trends you have going on – and if you’re looking at any of these trends to update your existing style. If your home needs a bigger upgrade than just some new design elements, I can always help you sort through the financing options. Call text or email me anytime!
Economic News 10 Mar
Last month, the US Supreme Court issued a verdict on the tariff lawsuit. The ruling invalidates a large portion of the tariffs that Trump implemented in 2025.However, there are other ways that he can introduce import taxes. Here’s a chart showing some of the other means these tariffs could be put back on the table:
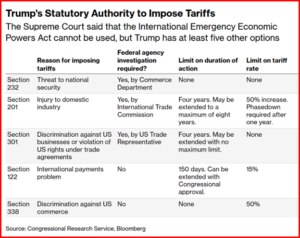
Source: Congressional Research Service, Bloomberg
Realistically, most affected tariffs will likely be reinstated by other means – and a temporary blanket 10% tariff already has. Trump has already ordered a raft of trade investigations that should allow him to enact more permanent tariffs, too.
While this could be good news for Canada, in the immediate future, it only increases uncertainty, further dampening consumer and business confidence and increasing the likelihood that spending decisions, whether for housing or business fixed investment, will be postponed.
Personal Finance 1 Mar
Fraud awareness starts with recognizing red flags in calls, emails, texts, and online messages.
March is fraud awareness month, a great reminder that no matter who you are, scams are lurking right around the corner (or in the next email, call or post!). 2026 will undoubtably throw more sneaky, compelling, and downright dastardly scams than ever. So, we’re going to look at how and why fraud scams work, spotlight the techniques scammers use, give you tips on how to recognize a scam, and teach you what you can do to protect yourself.
Why do scams work?
Here are my 4 E’s of an effective scam:
Ego: Some people think they are too smart to fall prey. Their overconfidence says they don’t need to be cautious and that exposes them to unnecessary risk.
Evolution: Scams are diverse and sophisticated – it’s not a Nigerian Prince asking you to share his millions anymore! The constant changing and diversification of scams is fuelled by new technology, making it harder to spot a fake.
Education: A lack of awareness means you’re a step behind a fraudster, and you’re unlikely to recognize the newest and greatest plots.
Exposure: We’re online a LOT, constantly seeing fake ads, sharing our email addresses to get discount codes, commenting on social media posts – you name it. We constantly expose ourselves to predators.
Techniques Scammers Rely On
The first strategy scammers use is emotional manipulation. They’ll create uncomfortable feelings like fear or urgency to get you to act quickly. They’ll also go the sympathy and goodwill route to appeal to your good nature and empathetic side so you help them.
The second strategy scammers use is cognitive bias. It’s our predisposition to a certain mindset that would make you more willing to comply. A few examples:
Optimism Bias: You don’t automatically suspect a scam
Truth Bias: You assume people are telling the truth
Authority Bias: You trust and comply with authority figures (like police or government)
The third strategy scammers use is influence. They’ll compliment you or pretend to have similar likes so they build a relationship with you. They’ll act as experts or authorities so that you trust them. And, they’ll commit to it, starting slow and building over time and increasing their requests.
How Did Scammers Get So Good?
They practice. They aren’t afraid to fail. They don’t take no as an answer. And, perhaps most importantly, they embrace technology. It catches victims unaware and drastically improves their reach and persuasiveness. Here are their fanciest tools.
AI: AI makes it easy for scammers to create professional-looking websites, social media content, online ads, fake photos, persuasive emails and texts, and so much more.
The Dark Web: Scammers can buy nearly any data they want, plus fake identities, malware tools, stolen credit card numbers, ransomware, a fake escrow service or even hire hackers.
Deepfakes: Fake videos that clone real people and real voices are easy to create with free or cheap specialized software. These fake videos can promote products, laud fake charities or causes needing donations, even endorse ponzi schemes and pump-and-dump investments.
Spoofing software: Fraudsters can mimic legitimate phone numbers, emails, or websites and even trick you into thinking you’re dealing with a real person you know.
Red Flags
Scammers aren’t just straight up asking for your SIN and banking info anymore. Here are some common themes to watch for:
Urgency, including limited time offers or requests to act now
Threats, like an account will be closed, you’ll be arrested, or a fine is forthcoming
Uncommon payment forms, like wanting gift cards, cryptocurrency, or Venmo transfers
Secrecy, warning you not to tell friends or family or alert law enforcement
Poor quality, like spelling errors, weird links, or other telltale signs AI has been hard at work
Reciprocity, as in you get hired but you pay for your own training, or you won a prize but you have to pay to receive it
How to Avoid Falling for Scams
If you don’t want to be blindsided by a scam, the first step is to know that scams exist. Staying current on the latest schemes will go a long way. Be skeptical about almost everything online! Installing ScamShield, call blocking or anti-virus software can help prevent a scam artist from contacting you. Multi-factor authentication is a great way to stop scammers from accessing your online accounts.
If you get faced with a scam, take a step back and think about the legitimacy of the situation. Call a trusted friend or loved one and run the situation by them. Just hearing it out loud might make you come to your senses! Practice saying no. Disconnect from the situation and reach out to the company independently (like the CRA, bank, cell phone company or store) to confirm the request or offer is real. Finally, monitor your accounts for any unauthorized activity if you think you might have given away too much information.
Conclusion
If you’d like to learn more, the FCT fraud insights centre is a great place to start. Or, get your information in video form in Mastercard’s Anatomy of a Scam docuseries. Hopefully shining a spotlight on these tactics keeps your safety top of mind. Or as Bert and Gert would say, “Stay Alert, Stay Safe”!
Mortgage Tips 23 Feb
A reverse mortgage can help homeowners 55 and older access home equity while continuing to live in their home.
Visualize this: It’s 1986. You’re an accountant in Vancouver. You’re seeing seniors living longer, healthier and more self-sufficient lives than ever. But they don’t have enough cash to pay their day-to-day expenses.
You want to help them. So, you create a financial product that lets them access home equity without giving up ownership.
You call it… the Canadian Home Income Plan, and lovingly refer to it as a CHIP. Your product – a reverse mortgage – gives seniors a way to stay in their homes, access the equity without selling, and have complete flexibility and control over the funds. It has a slow start, but over the next decade it catches on across Canada.
Fast forward to 2026 and the reverse mortgage has evolved into a useful tool for so many Canadians. We’ve seen a 40% increase in usage of reverse mortgages in the past 3 years alone! There are several reasons for this, including skyrocketing property values, inflation driving up the cost of living, people living longer and healthier after retirement, and a whopping 71% of those over 75 still owning homes. So, older Canadians are opting to supplement their income with home equity to maintain or improve their standard of living in retirement.
What are the Basics of a Reverse Mortgage?
A reverse mortgage is available exclusively to homeowners aged 55 and older; all applicants must meet that minimum age. You can access anywhere between 15-55% of the value of your home, with your age and the location playing the biggest roles in the amount.
With a reverse mortgage, you can take out money in four different ways:
Also of note is that you must live in the home, maintain the property, and ensure property taxes and insurance are both paid and current. You can get up to 3 reverse mortgages and even qualify for one on multi-unit properties (up to 6 units).
What are the Benefits?
A reverse mortgage doesn’t depend on your credit score or your income for qualification. In fact, you don’t need to have any income at all! You also maintain complete ownership of your home and continue to live in it and build equity.
Another set of benefits are that the funds aren’t considered income, so they’re not taxed and don’t impact any pension or benefits you qualify for. You can even use this as part of your tax strategy (do consult a financial planner about this though).
What Can I Use a Reverse Mortgage for?
These funds are extremely flexible, so you can use them for nearly anything. A few common ways Canadians use them are:
What Will a Reverse Mortgage Cost?
There are two types of costs you’ll encounter with a reverse mortgage.
First, like any mortgage, you’ll be charged interest. The rates are typically 1-2% higher than a regular mortgage, but you have the same flexibility with fixed or variable rates in various terms.
Second, you’ll have upfront costs to fund the reverse mortgage. You’ll need to get independent legal advice, an appraisal on your home, and you’ll most likely pay a lender or setup fee. Those three items will typically cost $1500 – $3000. You might be able to negotiate the rate or even find a promotion that waives the setup fee, so using a mortgage professional to shop around could save you money.
How do I Get Out of a Reverse Mortgage?
Much like a regular mortgage, you can pay off the amount owing in full at the end of the term without penalty. You can also make regular payments to bring down the balance. Lenders may also impose early repayment fees depending on the terms and conditions.
Alternatively, if you sell the property, you repay the amount in full at the time of sale. In the case of death, your reverse mortgage must also be repaid in full, before your estate is disbursed.
Are Reverse Mortgages Regulated?
Yes. The industry is regulated by the Office of the Superintendent of Financial Institutions (OSFI). They’re considered a non-recourse loan, meaning you’ll never have to repay more than the property is worth or sold for. You often see this feature advertised by lenders as a ‘no negative equity guarantee’, but know that’s a legal requirement here in Canada.
Are Reverse Mortgages a Scam?
No. They’re a legitimate and useful way for people to access home equity without selling their home. They’ve been approved and endorsed by the Canadian Association of Retired Persons (CARP), and members can even qualify for a $250 fee rebate upon funding. Plus, the Ontario Teachers Pension Plan invests in one of the main reverse mortgage companies.
However, like any financial product, the reverse mortgage market sees its share of scams. Be sure to use a licensed and experienced mortgage professional to avoid them. Look out for anyone one asking you to sign over the title to your home (never do this), or contractors offering to do the paperwork and get funding for you to fund upgrades or renovations. Those are big red flags!
Are there Alternatives to a Reverse Mortgage?
You always have options! A Home Equity Line of Credit (or HELOC) lets you take out equity and offers up to 80% of the value of your home (although you need income to qualify). You could also sell your home and downsize, rent, or move into another type of residence. No matter what route you go, you’ll want to look at the total cost of each option to help you make the best decision.
What Are the Next Steps to Getting a Reverse Mortgage?
I’d love to help you explore your options. There are several Canadian financial companies that offer reverse mortgages in 2026, each with different fees, requirements and features. I would be happy to compare them and help you pick the best choice for your unique situation. Let’s set up a call to discuss.
Let’s explore mortgage options that fit your goals and financial situation.
Jag Dhamrait
Mortgage Agent Level 2
Phone: 647-883-7790
Email: jag@jagdhamrait.com
Economic News 3 Feb
Dr. Sherry Cooper shares economic insights on Canada’s trade diversification, global partnerships, and economic outlook.
Amid significant shifts in global trade dynamics, Canada is redefining its position on the world stage. While the United States continues to make headlines with its assertive trade policies, other nations—Canada included—are forging ahead, adapting and expanding their international relationships.
Last week, Prime Minister Mark Carney’s visit to Beijing marked the first Canadian prime ministerial trip to China since 2017, culminating in a landmark trade agreement. Canada lowered its tariff on Chinese electric vehicles, while China reciprocated by reducing tariffs on Canadian canola seed. Carney emphasized the importance of renewing and strengthening the Canada-China partnership, asserting that these efforts signal a move toward a new global order, with Canadian exporters increasingly seeking opportunities beyond the US market.
Impact on Economic Sectors
The prevailing uncertainty surrounding trade—driven by tariffs and shifting alliances—has contributed to a decline in housing market activity, particularly in Ontario and British Columbia. In contrast, Quebec’s housing market remains more robust, although tariffs on aluminum and lumber have dampened broader economic activity in the province and across Atlantic Canada.
Despite widespread concern about these developments, Canada’s outlook for broadening trading partnerships is stronger than many anticipate. The country possesses substantial competitive advantages that position it well to meet international demand over the next decade.
Canada’s strengths lie in its rich natural resources, including oil and gas, uranium, critical minerals, food and agriproducts, fresh water, and Arctic access. These endowments provide a solid foundation for trade diversification.
Historically, 75% of Canadian exports have gone to the US, with agreements like CUSMA offering tariff protections for many Canadian goods. However, recent developments and strategic initiatives are opening new opportunities, especially in the energy and agri-food sectors, where Canada’s geography, resource reserves, and trade agreements align with growing demand from Europe and Asia.
Cross-Cutting Advantages
Canada is a leading global supplier of scarce commodities, including crude oil, natural gas, potash, canola, and other agri-food products. Its status as the world’s largest producer of potash is crucial to the US fertilizer supply, and there is significant potential to expand exports to major importers like Brazil, India, and China.
Canada benefits from a robust network of trade agreements, including CETA with the EU and CPTPP with Asia-Pacific economies. These agreements lower barriers for exports to Europe and Asia, offering advantages over non-preferential competitors. The country’s trade strategy now aims for a 50% increase in overseas (non-US) exports, a goal already being met ahead of schedule in some sectors.
Canada’s reputation as a politically stable, rules-based, and relatively low-carbon supplier is increasingly valued by global buyers prioritizing security of supply, especially in energy and food. This reputational premium is particularly important for European and Indo-Pacific customers seeking to mitigate risks posed by Russia and certain Middle Eastern suppliers.
The Trans Mountain Expansion (TMX) and LNG Canada projects have significantly increased Canada’s pipeline and liquefaction capacity, providing direct access to Pacific markets. Since 2017, TMX has enabled a 130% rise in energy exports to overseas destinations, with LNG shipments reaching Japan, South Korea, China, and Malaysia. Chinese purchases of Canadian oil have reached all-time highs.
For North Asian markets, Canadian Pacific Coast LNG shipments are much faster than those from the US Gulf Coast, cutting approximately 20 days off voyages to South Korea. This geographic advantage, combined with Canada’s vast gas reserves and political stability, makes it a structurally competitive supplier to Asian gas markets.
Following the Ukraine conflict, Europe and Asia have strong incentives to diversify their energy sources away from Russia. Canada’s new export infrastructure directly supports this demand, with the global LNG market expected to remain tight through the mid-2020s, offering a window for new Canadian supply to secure long-term contracts.
Canada’s primary advantages are in upstream metals and minerals, such as iron ore and critical minerals, rather than in finished steel and automotive products. Metal and non-metallic mineral exports have grown rapidly—up about 74% since 2017—driven by gold and other metals.
For steel, aluminum, and auto parts, Canada’s ability to market low-carbon content and secure supply is a key differentiator, especially in jurisdictions tightening carbon and supply-chain regulations. While Canada’s participation in multiple free trade agreements provides tariff preferences in Europe and Asia, the integration and scale of the North American auto platform continue to present challenges for diversification in finished goods.
Canada plays a central role in global canola and potash markets and faces strong demand from large agricultural economies outside the US. The country supplies roughly 85–90% of US potash imports but is positioned to pivot toward growing markets such as Brazil, India, and China if US trade becomes less attractive.
China is a major buyer of Canadian raw canola seed and has greater processing capacity than other markets. Canada’s access to Asian and European trade channels further supports diversification. According to Farm Credit Canada, approximately $12 billion CAD in food and beverage exports could be redirected from the US to other markets or to domestic buyers, highlighting significant potential for reallocation.
Canada’s surplus potash supply helps keep domestic fertilizer costs low, allowing grain and oilseed exports to remain competitively priced in third markets. Combined with high standards for food safety and sustainability, Canada presents a compelling value proposition in premium and bulk agri-food markets.
In the near term, “water exports” are primarily realized through hydroelectric power from resource-rich provinces, rather than bulk water shipments. These hydro resources support green power exports, particularly to the northeastern US, and may contribute to future cross-border electricity grids.
As climate risks grow, Canada’s abundance of water and arable land creates long-term advantages in producing water-intensive goods such as grains, oilseeds, forestry products, and certain metals—positioning the country to supply water-stressed regions globally.
Canada’s federal strategy now explicitly positions trade diversification as central to risk management and economic resilience. Dedicated tools and financing, including Export Development Canada and trade commissioner services, are helping exporters access non-US markets. Combined with private-sector investments in logistics and port capacity, these efforts continue to reduce the costs and barriers associated with reorienting exports.
Canada’s structural advantages enable a gradual reduction in marginal dependence on the US, particularly in energy, agri-food, and some metals and advanced manufacturing sectors. However, full substitution in autos and certain processed goods remains unrealistic and inefficient due to the deep integration of the North American market. Overall, Canada’s expanding network of trading partners and robust resource base position it well for a resilient economic future.
As these successes mount, Canadian consumer and business confidence will rise, re-igniting pent-up demand in housing. As we move through this transition year, optimism will mount, and reduced housing prices, combined with lower mortgage rates, will return housing activity to more normal levels in the hardest-hit provinces of Ontario and British Columbia.
Personal Finance 27 Jan
|
|||
|
Home Tips 20 Jan
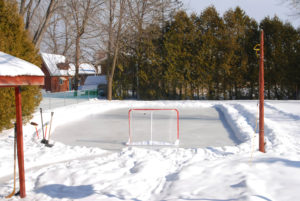
A common winter scene of a backyard hockey rink in Canada
A skating rink in your own backyard? Yes, please!
A skating rink is a great way to keep kids busy, stay active yourself, entertain guests, or even use as a conversation-starting background to your social media content. Here’s how to make this easy, enjoyable feature at home this month.
I hope you give this a try – and don’t let my invite get lost in the mail if you do!

